
Understanding Beyond Value Chain Mitigation (BVCM) under SBTi
The Science Based Targets initiative (SBTi) established the Corporate Net-Zero Standard to provide a clear, science-aligned blueprint for corporate decarbonization. Within this framework, corporate responsibility is divided into two distinct components: mandatory internal decarbonization across Scopes 1, 2, and 3, and voluntary climate action outside the corporate boundary. The latter is defined as Beyond Value Chain Mitigation (BVCM).
BVCM addresses an operational reality: even aggressive decarbonization trajectories leave an emissions footprint during the multi-decade transition to net-zero. SBTi expects companies to reduce value-chain emissions by at least 90 percent by 2050 (or earlier for specific sectors) to claim net-zero status. However, relying solely on deep abatement allows substantial cumulative greenhouse gases to enter the atmosphere during that multi-year ramp-down. BVCM encourages organizations to finance external climate mitigation concurrently with internal reductions, ensuring broad planetary impact while corporate operations decarbonize.
For sustainability directors, procurement executives, and risk officers, determining which credit types satisfy BVCM requirements involves evaluating permanence, additionality, verification standards, and future accounting utility. Durable carbon removal technologies, particularly biochar carbon removal (BCR), occupy an increasingly important position within BVCM portfolios.
The Mitigation Hierarchy: Abatement, BVCM, and Neutralization
To position biochar credits accurately within an SBTi-aligned program, organizations must distinguish between BVCM and net-zero neutralization. SBTi outlines a sequential mitigation hierarchy that prevents carbon credits from substituting for internal operational efficiency.
- Value Chain Abatement: Direct mitigation of Scope 1, 2, and 3 emissions against near-term and long-term science-based targets. Carbon credits cannot be counted as emissions reductions toward these targets.
- Beyond Value Chain Mitigation (BVCM): Voluntary financing or purchasing of mitigation outcomes outside the corporate perimeter during the transition. BVCM does not offset internal emissions for near-term target accounting; instead, it demonstrates corporate contribution toward global net-zero goals. Both emissions avoidance and carbon removals qualify for BVCM.
- Neutralization: The permanent removal and storage of counterbalancing carbon for any residual emissions (up to 10 percent of the baseline) once a company achieves its long-term science-based target. Neutralization strictly requires carbon dioxide removal (CDR) with durable storage.
Because BVCM permits both avoidance and removal credits, companies have significant latitude in portfolio construction. However, progressive sustainability teams increasingly direct BVCM capital toward durable removals like biochar to prepare their procurement mechanisms for eventual neutralization obligations.
Why Durable Removals Matter in BVCM Portfolios
Historically, corporate offsetting programs relied on avoided deforestation or renewable energy certificates. While these activities remain eligible under various voluntary frameworks, the voluntary carbon market and corporate governance standards now demand higher integrity, clear permanence, and traceable carbon accounting.
Short-duration biological sinks, such as afforestation and soil carbon enhancement, face physical reversal risks from wildfires, pests, droughts, and land-use changes. These non-permanence risks require continuous monitoring and extensive buffer pool contributions. In contrast, durable carbon dioxide removal isolates atmospheric carbon in geological, mineral, or recalcitrant solid forms that resist biological degradation over centuries.
BVCM guidance from SBTi explicitly identifies the scaling of durable carbon removal as an urgent global priority. By allocating a defined portion of BVCM budgets to high-durability mechanisms, enterprises accelerate market liquidity, support industrial capacity, and de-risk supply access ahead of mandatory neutralization dates.
Where Biochar Fits: Technical Permanence and Carbon Chemistry
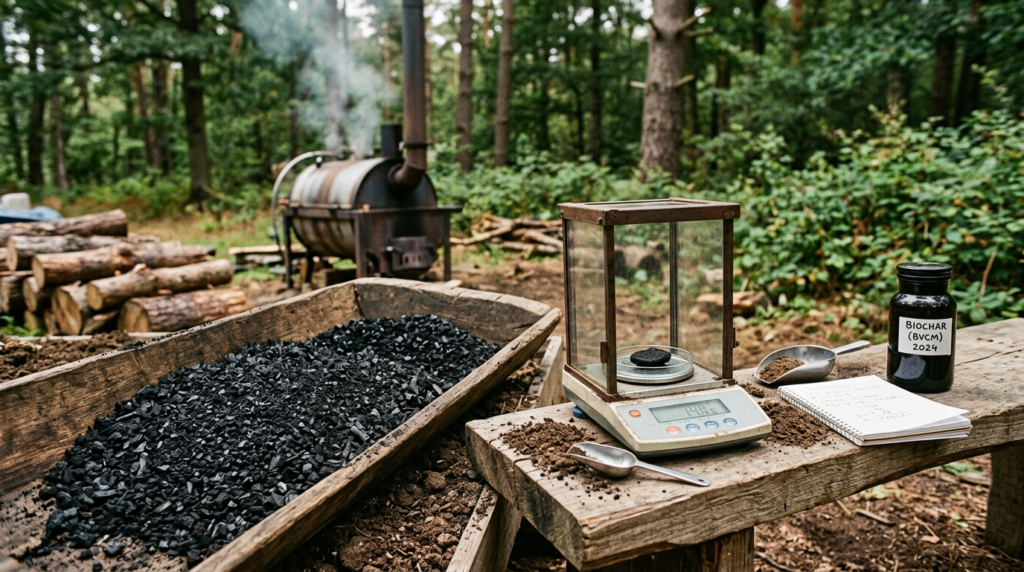
Biochar carbon removal qualifies as an engineered, durable terrestrial removal. The process converts residual biomass—such as agricultural residues, forestry waste, or invasive species—into a stable, solid carbon material through pyrolysis, which is thermochemical decomposition occurring in oxygen-limited environments.
During photosynthesis, plants capture atmospheric carbon dioxide to form organic biomass. Left to decompose or burn in natural cycles, this biomass returns carbon to the atmosphere as carbon dioxide or methane. Pyrolysis alters the underlying chemical structure, converting unstable aliphatic carbon into dense, polycyclic aromatic carbon rings. This recalcitrant carbon resists microbial digestion and oxidation.
The durability of biochar depends on pyrolysis operating temperatures and the resulting molar hydrogen-to-carbon (H/Corg) ratio. Standard methodologies mandate an H/Corg ratio below 0.7, with high-temperature production frequently achieving ratios below 0.4. Peer-reviewed physical chemistry demonstrates that biochar meeting these metrics retains the majority of its sequestered carbon in soils or inert materials for centuries, comfortably exceeding the operational permanence thresholds expected of high-integrity BVCM investments.
Registry Methodologies and Quality Criteria for SBTi Alignment
Not all biochar projects satisfy the rigorous quality requirements necessary for institutional BVCM reporting. SBTi points to major carbon crediting integrity initiatives, such as the Integrity Council for the Voluntary Carbon Market (ICVCM) and its Core Carbon Principles (CCPs), to guide credit quality. For biochar carbon removal to withstand institutional scrutiny, it must be verified under rigorous registries.
Established methodologies include:
- Puro.earth (Puro Standard): Provides dedicated accounting for biochar production, requiring laboratory verification of H/Corg ratios, complete supply-chain life cycle assessments (LCAs), and strict tracking of end-use applications.
- Verra (VCS VM0044): Methodology for Biochar Utilization in Soil and Non-Soil Applications, outlining comprehensive baseline accounting, production emissions monitoring, and permanence modeling.
- Isometric Biochar Protocol: Sets strict durability baselines, continuous digital monitoring requirements, and standardized life cycle accounting.
- Climate Action Reserve (CAR): U.S. and international biochar protocols tracking feedstocks, processing emissions, and distribution pathways.
To qualify as high-confidence BVCM assets, biochar projects must establish additionality (proving the activity would not occur without carbon revenue), ensure non-depletion of primary forests, account for all processing and transport emissions, and verify that final application occurs in stable environments such as agricultural soils or construction materials.
Integration with dMRV and Audit Readiness
Corporate reporting standards are moving rapidly toward financial-grade scrutiny. Voluntary BVCM claims that cannot be defended with granular data expose organizations to greenwashing allegations and regulatory intervention under consumer protection and corporate disclosure laws.
Digital Monitoring, Reporting, and Verification (dMRV) transforms biochar accounting from periodic manual sampling into verifiable digital records. A robust dMRV architecture tracks:
- Feedstock sourcing through geographic origin verification, ensuring residues do not compete with food production or accelerate ecosystem conversion.
- Pyrolysis operational data, using IoT sensors to log continuous reactor temperatures, residence times, and syngas combustion efficiency.
- Output mass balances, cross-referencing biochar yields with laboratory-certified carbon contents.
- Chain of custody, documenting logistics, distribution channels, and soil application down to the field level.
For companies disclosing climate actions, this digital provenance ensures that BVCM claims are underpinned by auditable primary data. This aligns directly with external audit expectations and institutional reporting obligations.
Disclosures and Alignment: IFRS S1 and IFRS S2 Standards
The International Sustainability Standards Board (ISSB) has established global baseline standards for sustainability-related financial disclosures: IFRS S1 (General Requirements) and IFRS S2 (Climate-related Disclosures). When corporate entities engage in BVCM through the procurement of biochar credits, IFRS S2 requires clear reporting of these transactions within general-purpose financial filings.
Under IFRS S2, companies must disclose:
- The extent to which climate targets rely on the use of carbon credits.
- Which third-party schemes or registries verify and certify the credits.
- The physical nature of the underlying credits, explicitly distinguishing between emissions avoidance and carbon removals.
- The permanence of the mitigation outcome, including any contractual or scientific mechanisms used to address reversal risks.
- How the procurement fits into the corporate transition plan and broader capital allocation.
Purchasing verified biochar credits allows reporting entities to report carbon removals characterized by hundreds of years of permanence, documented additionality, and transparent registry retirement. Treating BVCM investments with the same rigor applied under IFRS 9, 7, and 15 ensures that commitments made on public sustainability dashboards match the notes in financial statements.
Financing Structures: Operationalizing BVCM with Biochar
Companies structuring BVCM programs typically adopt one of two standard approaches outlined in SBTi guidance: the money-for-money model or the ton-for-ton model.
The Money-for-Money Approach
In this model, an organization assigns an internal carbon price (e.g., a defined monetary fee per metric ton of unabated Scope 1, 2, or 3 emissions) to generate an annual mitigation fund. This fund is then distributed across external climate solutions. Because biochar carbon removals command prices reflecting their physical production infrastructure and permanence, a money-for-money allocation allows companies to blend purchases. An enterprise can allocate a portion of the fund to near-term biodiversity or community-based projects and reserve a specific tranche for high-durability biochar credits.
The Ton-for-Ton Approach
Under the ton-for-ton model, a corporation commits to financing external mitigation equivalent to a specific percentage of its annual unabated emissions. While matching 100 percent of residual corporate emissions with durable removals can require substantial capital, companies often structure phased programs. For example, an organization might match a small, growing fraction of its gross annual footprint with durable biochar removals today, systematically increasing that percentage as internal decarbonization reduces the gross emissions baseline.
Building Supply Resiliency for Future Net-Zero Claims
A critical operational reason to evaluate biochar within current BVCM programs is forward market capacity. As thousands of companies advance toward their 2030 and 2050 targets, the demand for verified, permanent carbon removals to achieve final neutralization will expand significantly. Analysts and market observers regularly project supply constraints for high-integrity removals toward the end of this decade.
By actively procuring biochar credits today as part of BVCM, enterprises achieve three strategic goals:
- Operational Testing: Developing the internal governance, accounting, and dMRV frameworks required to manage physical carbon removals before regulatory or stakeholder pressure intensifies.
- Supply Partnership: Establishing long-term off-take relationships with verified biochar producers, securing price stability and predictable volume allocations.
- Market Leadership: Demonstrating authentic climate contribution by financing physical, permanent carbon sinks rather than low-durability avoidance mechanisms that carry reputational liability.
Biochar carbon removal bridges the gap between near-term climate action and long-term net-zero integrity. By embedding durable biochar credits into Beyond Value Chain Mitigation portfolios today, organizations build defensible climate programs that withstand technical, financial, and regulatory scrutiny.
To evaluate biochar carbon removal procurement, structure your SBTi-aligned BVCM portfolio, or integrate dMRV and IFRS S2 disclosure advisory into your corporate climate roadmap, contact the sustainability advisory team at ForestTwin.